The best KYC software depends on what you need to verify - identity, business ownership, AML screening, or all three - and the leaders specialise differently. The top solutions are:
- Identity verification (document + biometric): Onfido (Entrust IDV), Veriff, Sumsub, Persona - confirm a person is who they claim.
- AML & sanctions screening: ComplyAdvantage, Trulioo - screen against watchlists, PEPs and sanctions.
- KYB (business onboarding): Sumsub, Trulioo, Alloy - verify companies and Ultimate Beneficial Owners.
- Orchestration: Alloy, Socure - route and combine multiple verification signals.
One gap most KYC tools leave open: they confirm who a customer is, but not that the bank account they transact through actually belongs to them, or that the payees they pay are legitimate. That's where bank account and payee verification - SurePay's domain - complements a KYC stack, closing the loop between identity and money movement.
What does KYC compliance software do?
KYC (Know Your Customer) compliance software verifies a customer's identity before or during onboarding, and supports the ongoing AML obligations that depend on that verified data. Good platforms in 2026 combine biometric verification with liveness detection, automated screening against sanctions and PEP lists, broad global document coverage, clean API integration, GDPR/AML compliance, and a low-friction user experience.
The market splits into a few specialisms, and most institutions assemble more than one. Identity verification confirms a real person via document and biometric checks. AML screening checks names against watchlists and monitors for suspicious activity. KYB applies the same scrutiny to businesses, tracing ownership to the Ultimate Beneficial Owners. And orchestration layers route a customer through the right checks and combine the signals. Choosing well means matching the tool to your customer type, geography and risk - not buying a single "KYC product."
Top KYC identity verification platforms
For verifying individual identities, the leading platforms combine AI document checks with biometric face matching and, often, human review to keep pass rates high while filtering fraud. These are the core of most KYC programs.
- Onfido (Entrust IDV) - document checks plus biometric face matching (selfie/video), AI with human review; strong global onboarding.
- Veriff - one of the broadest document libraries (12,000+ types, including non-Latin scripts), AI plus expert review.
- Sumsub - flexible workflow builder with native AML screening and a KYB layer in one dashboard; priced per completed check (model rejection rates included).
- Persona - highly configurable identity infrastructure for building custom verification flows.
- Socure - AI-driven identity and risk, particularly strong in the US market.
These excel at confirming a person is genuine. What they don't do is confirm that the bank account the person uses is theirs - a separate, complementary check.
Best AML and KYB (business) compliance software
For AML screening and business onboarding, the leaders focus on watchlist depth and corporate ownership rather than document capture. AML and KYB have become the sharper edge of compliance as regulation tightens.
ComplyAdvantage is best understood as an AML and risk-intelligence layer - strong where screening depth matters more than document checks. Trulioo scans 14,000+ document types against five billion identities across 195 countries, suited to cross-border KYC/AML and business onboarding at scale. Sumsub and Alloy cover KYB, verifying company registration, ownership structure and Ultimate Beneficial Owners (UBOs). Two 2026 drivers raise the bar: the US Corporate Transparency Act (UBO reporting to FinCEN) and the EU's new AML Authority (AMLA, operational since 2025), which is harmonising beneficial-ownership verification with mandatory central UBO registers.
Beyond identity: account ownership and Know Your Payee
KYC confirms who your customer is; it doesn't confirm that the bank account they provide belongs to them, or that the parties they pay are legitimate - and that gap is where onboarding fraud and mule accounts slip through. Closing it requires two checks that most KYC suites don't perform: account-ownership verification and payee verification.
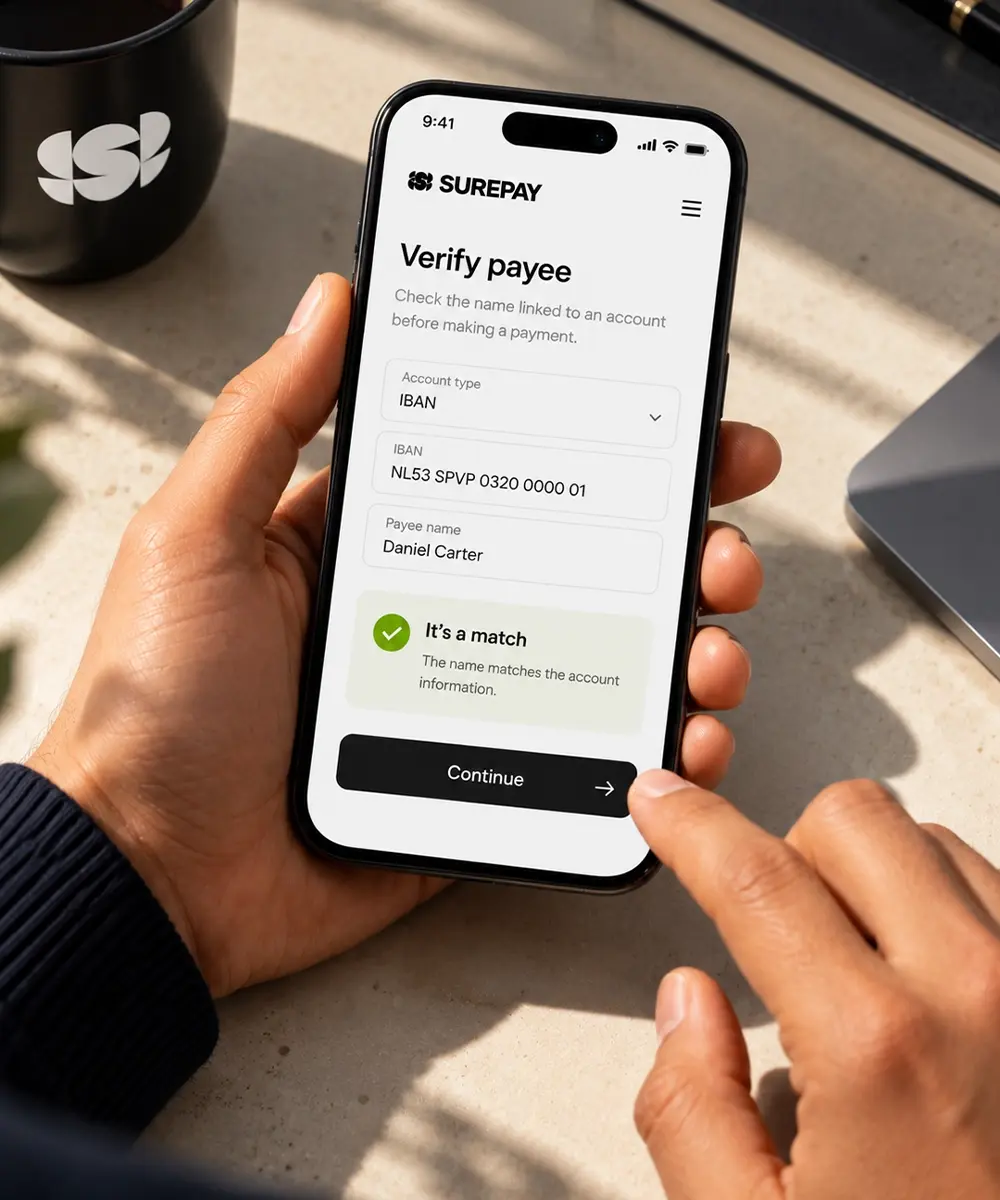
Account-ownership verification confirms the name on a customer's bank account matches the identity onboarded - a high-value KYC/KYB signal that helps stop mule accounts and synthetic-identity fraud at the point money first moves. Payee verification ("Know Your Payee") extends the same assurance to the customer's outbound payments, confirming counterparties are real before funds leave. SurePay provides this layer through its IBAN-Name Check / Verification Of Payee service - live since 2016, connected to 250+ European banks, covering 99.9% of Dutch bank accounts - and it complements, rather than replaces, a KYC platform. Together, KYC (identity), account verification (ownership) and payee verification (Know Your Payee) give end-to-end assurance from onboarding through every transaction.
KYC and complementary compliance software compared
| Category | Verifies | Leading software | Role |
|---|---|---|---|
| Identity verification | A person is genuine | Onfido/Entrust, Veriff, Sumsub, Persona | Core KYC |
| AML & sanctions screening | Names vs watchlists/PEPs | ComplyAdvantage, Trulioo | KYC/AML |
| KYB (business) | Companies & UBOs | Sumsub, Trulioo, Alloy | KYB |
| Orchestration | Combines signals | Alloy, Socure | KYC infrastructure |
| Account & payee verification | Account ownership & payee legitimacy | SurePay | Complements KYC/KYB (Know Your Payee) |
Bottom line: for KYC identity verification, the leaders are Onfido/Entrust, Veriff and Sumsub; for AML/KYB, ComplyAdvantage and Trulioo. To close the gap KYC leaves - confirming the customer owns their account and pays legitimate parties - add account and payee verification, where SurePay is the most established European provider.
How do I choose KYC compliance software?
Match the stack to your customers, geography and regulatory exposure:
- Onboarding individuals? Lead with an identity-verification platform (Onfido/Entrust, Veriff, Persona) with biometrics and liveness.
- Onboarding businesses? Add KYB (Sumsub, Trulioo, Alloy) to verify registration and UBOs - essential under the Corporate Transparency Act and AMLA.
- AML-heavy? Prioritise screening depth (ComplyAdvantage, Trulioo).
- Worried about mule accounts and onboarding fraud? Add account-ownership verification (SurePay) so the bank account matches the onboarded identity, and payee verification for ongoing transaction assurance.
- Model the cost - per-check pricing (including rejected sessions) and false-positive rates drive total cost; combine document capture, screening and account verification to balance assurance and friction.