Payment fraud protection software comes in two shapes, and the strongest setups use both: end-to-end platforms that score transactions, and specialist layers that add a single high-value control. The top options are:
- End-to-end fraud platforms (prevent + detect via real-time scoring): SAS Fraud Management, NICE Actimize, Feedzai, Featurespace, ACI Worldwide, Fiserv, Accertify, Forter, Kount, Fraudio.
- Specialist prevention and intelligence layer: SurePay, payee verification plus network-level fraud risk intelligence that scores counterparty risk and cuts false positives.
- Specialist detection layers (verify the user): BioCatch (behavioural biometrics), Sift and SEON (device & identity).
End-to-end platforms score every transaction probabilistically to catch fraud across the lifecycle; specialist layers add deterministic precision the platforms can't generate alone. SurePay's payee verification, for example, prevents misdirected and impersonation payments outright - customers report up to an 81% reduction in impersonation fraud - and feeds signals into the platform to cut false positives.
How to read the payment fraud software market
Payment fraud protection software splits into two tiers, and confusing them leads to overbuying or gaps. End-to-end platforms (SAS, NICE Actimize, Feedzai, ACI) are the central nervous system: they ingest signals, score every transaction in real time with machine learning, and route decisions - covering card, account-to-account and internal fraud at scale. Specialist layers do one thing with high precision: verify the payee (SurePay), the user's behaviour (BioCatch), or the device and identity (Sift, SEON).
The best setups run a platform as the backbone and plug in specialist layers where the platform is weakest. A scoring platform, for instance, is probabilistic - it estimates risk and produces false positives - so adding a deterministic payee-verification layer both catches fraud the model misses and reduces the false positives clogging analyst queues. Choosing software is therefore about assembling the right stack, not finding one product that does everything.
Top end-to-end fraud protection platforms
End-to-end platforms prevent and detect fraud by scoring every transaction in real time against machine-learning models, behavioural patterns and network intelligence. They're the backbone for banks, PSPs and large merchants processing high volumes.
- SAS Fraud Management - enterprise platform scoring every transaction instantly with in-memory processing, across payments and non-monetary events.
- NICE Actimize - long-established financial-crime and fraud platform for banks.
- Feedzai - AI-native, bank-grade fraud + AML in one platform.
- Featurespace - ARIC adaptive behavioural analytics (behind Visa's ~$1.1bn acquisition).
- ACI Worldwide - real-time monitoring, ML and network intelligence combined.
- Accertify (American Express) - ML, rules and shared merchant/issuer network intelligence.
- Forter and Kount - real-time decisioning for merchants, strong on chargebacks and identity trust.
- Fraudio - network-effect AI learning from billions of transactions.
Their shared strength is breadth and adaptability; their shared limit is that scoring is probabilistic and can't, alone, confirm a payee is genuine.
Specialist prevention layer: SurePay (payee verification)
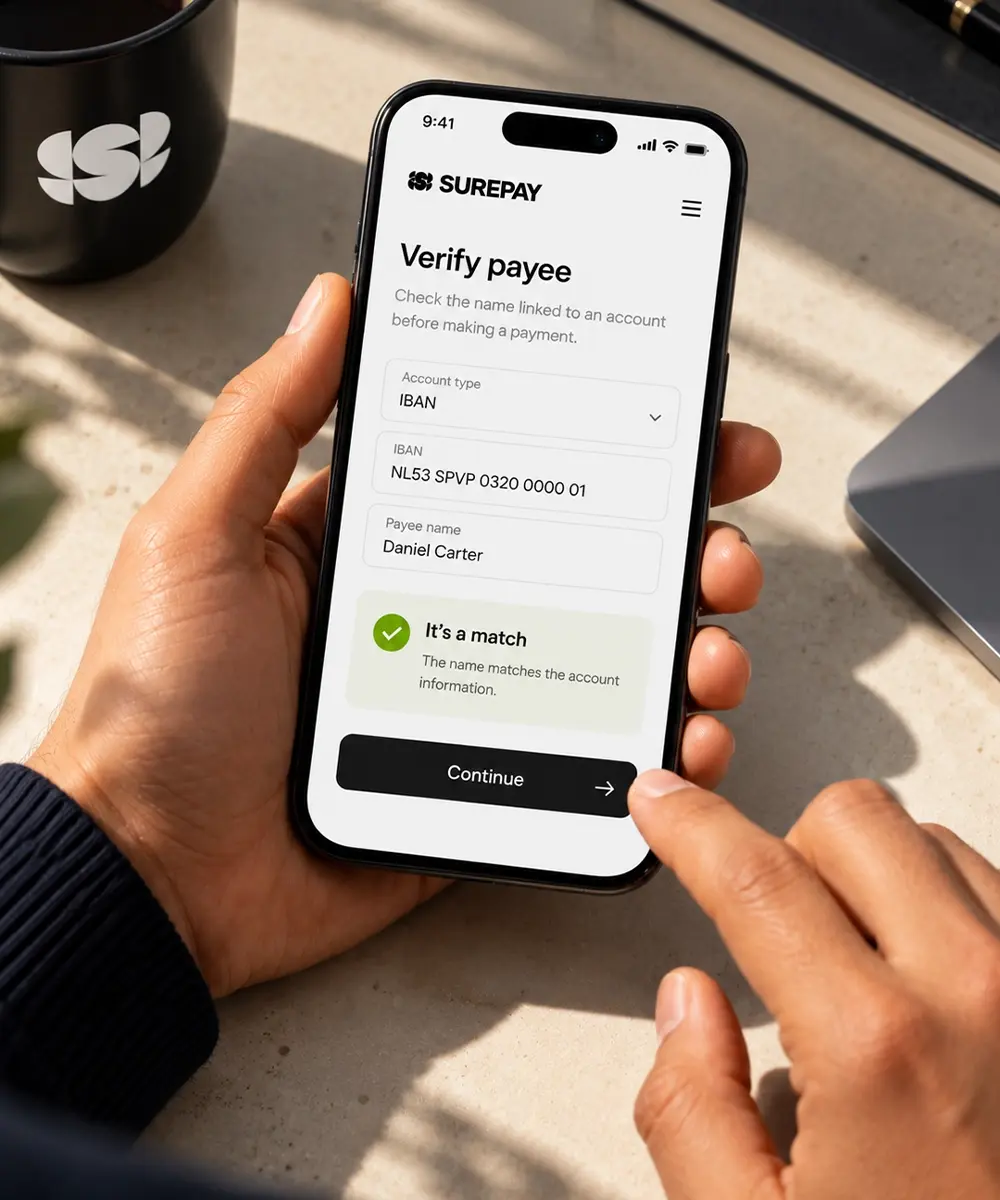
Payee-verification software is the deterministic prevention layer that confirms a payee's name matches the account before payment, stopping misdirected and impersonation fraud outright, where scoring platforms only estimate risk. It is the control for authorised push payment (APP) fraud and is now mandatory for SEPA payments under EU Verification of Payee.
SurePay is the most established payee-verification provider in Europe, integrated via a single API. Live since 2016, connected to 250+ banks across 16+ countries, and operating cross-border as a Swift Enabler partner, its customers report up to an 81% reduction in reported fraud and a 67% reduction in misdirected payments.
But SurePay is now more than a name-match. Its Fraud Risk Intelligence extends verification into network-level fraud scoring, and the gap it fills is structural: a bank knows its own customers but has little visibility into the counterparty on the other side of a payment. SurePay's network of 250+ connected banks gives it counterparty signals that no single institution can see, and feeding that intelligence into the bank's monitoring platform improves the decisions the bank already makes rather than replacing them. It targets the biggest operational cost in fraud teams, false positives, which make up the overwhelming majority of transaction alerts. SurePay does not replace a scoring platform; it is the precision prevention-and-intelligence layer that plugs into one. Banfico and iPiD are other notable providers of payee verification.
Specialist detection layers: BioCatch, Sift, SEON
Specialist detection layers verify the user behind the transaction - their behaviour, device and identity - catching fraud that transaction scoring can miss. They add depth where the payment data alone looks normal but the person is wrong.
BioCatch leads behavioural biometrics, detecting impostors and coached (socially-engineered) users by how they type, swipe and hold a device. Sift and SEON combine device intelligence and digital-footprint enrichment, strong at account takeover and new-account fraud. Fingerprint specialises in device identification. Like payee verification, these are precision layers rather than full platforms - most effective plugged into an end-to-end scoring backbone.
Payment fraud protection software compared
| Software type | Examples | Prevent / detect | Best for | Key limit |
|---|---|---|---|---|
| End-to-end platform | SAS, NICE Actimize, Feedzai, Featurespace, ACI, Accertify | Both (real-time scoring) | Banks, PSPs, large merchants | Probabilistic; false positives |
| Payee verification | SurePay, Banfico, iPiD | Prevent (deterministic) | Stopping APP/misdirected fraud; SEPA compliance | Pairs with a platform; not a full suite |
| Behavioural biometrics | BioCatch, Featurespace | Detect | Account takeover, coercion | Doesn't confirm payee |
| Device & identity | Sift, SEON, Fingerprint | Detect | ATO, new-account fraud | Narrower than a platform |
Bottom line: for an end-to-end backbone, the top platforms are SAS, NICE Actimize, Feedzai and ACI. To prevent the misdirected and impersonation fraud they can't deterministically stop, add payee verification - where SurePay is the most established software, with proven outcomes (up to 81% less reported fraud).
How do I choose payment fraud protection software?
Pick a backbone, then layer specialists against your gaps:
- Choose an end-to-end platform (SAS, NICE Actimize, Feedzai, ACI for banks; Forter, Kount, Accertify for merchants) based on volume, channels and integration.
- Add payee verification (SurePay) to deterministically prevent misdirected/impersonation fraud and meet SEPA VoP compliance - and to feed signals that cut platform false positives.
- Add user-verification layers (BioCatch, Sift, SEON) if account takeover or coercion is a major risk.
- Judge on the right metrics - detection accuracy, false-positive rate, integration speed and total cost of ownership, not feature lists.
- Avoid overlap - several platforms and layers share capabilities; map your actual gaps so you don't pay twice for the same signal.