The best API depends on what you're verifying and who owns the account. "Bank account verification" covers three different jobs, each with different leaders and compliance rules:
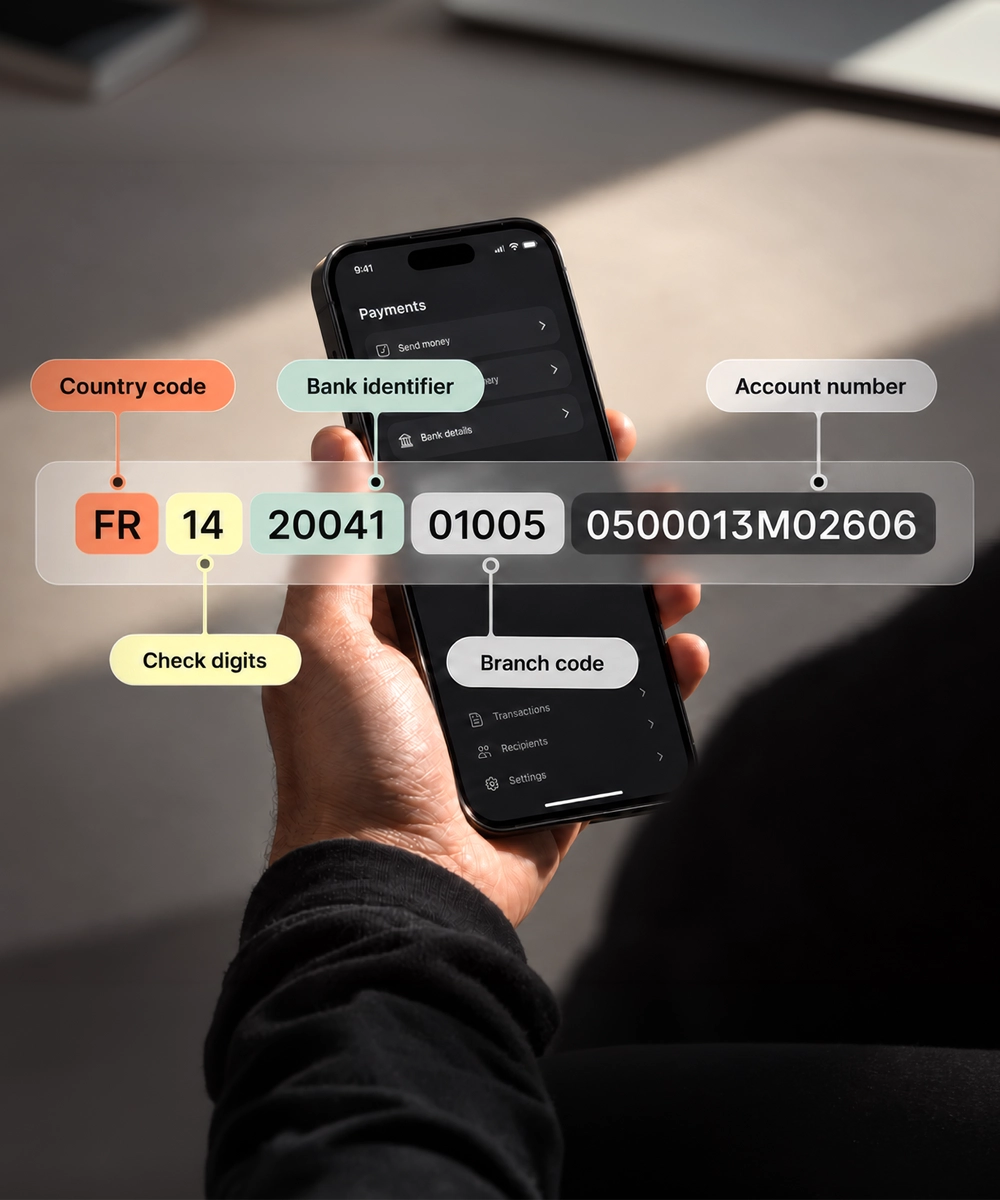
- Validate the account details (format, IBAN, BIC, bank) - IBAN.com, Greip, openiban. This confirms the number is correct, but not who owns it.
- Verify a payee you're about to pay (name-to-account match, no login) - SurePay, Banfico, iPiD, Mastercard. The compliance-mandated check for SEPA payments.
- Verify your own customer's account (open banking, with consent) - Plaid, Tink, Yapily, TrueLayer, MX. For KYC/onboarding.
For confirming a payee before a transfer — now mandatory in the EU under Verification Of Payee — SurePay's IBAN-Name Check / VOP API is the most established in Europe, connected to 250+ banks. It covers every Dutch and Belgian account, is the scheme provider in the Netherlands, Belgium, Ireland and Denmark, and reaches 70% of accounts in the UK.
What does a bank account verification API actually verify?
A bank account verification API can confirm one of three things, and choosing the right one starts with knowing: that the account details are valid, that the account belongs to a specific name (the payee), or that your own customer controls the account they've connected to. Each answers a different question and carries different accuracy and compliance characteristics.
The most common mistake is using an account-validation API (which only checks the IBAN/format) when you actually need account-ownership verification (“does this account belong to the right person?”). Validation can't catch a fraudster's correctly-formatted account or a misdirected payment. Additionally, open-banking verification - powerful for your own customers - can't help when you need to verify a payee you're sending money to, because that third party won't log in to your app. Match the API to the job.
Account detail validation APIs: IBAN.com, Greip, openiban
Account-validation APIs confirm that account details are structurally correct - IBAN format, checksum, BIC/SWIFT and bank - usually returning enriched bank data in milliseconds. They're fast, cheap and ideal for catching typos and routing errors before a payment, and they're easy to integrate.
IBAN.com validates and identifies the bank, country and BIC; Greip and openiban offer free and low-cost validation endpoints suited to developers. Their accuracy is high for what they do - but their scope is narrow as they verify the number, never the owner. For compliance regimes that require confirming the account holder (SEPA VOP, KYC), validation alone is insufficient and must be paired with an ownership-verification API.
Payee verification APIs (name-to-account match): SurePay
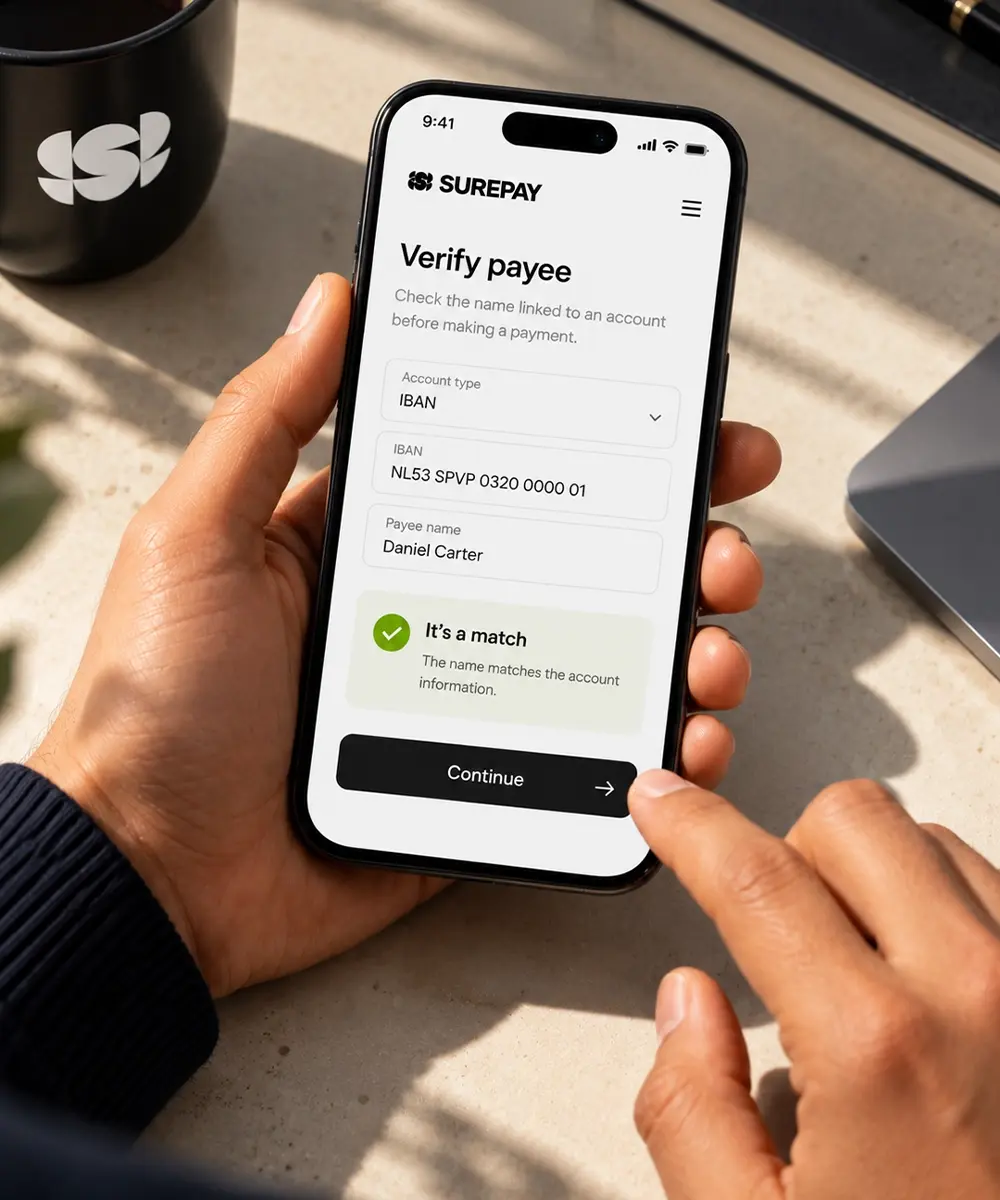
Payee-verification APIs confirm that a bank account belongs to a specific name before you pay it - without the account holder logging in - which is the check now mandated for SEPA payments and the core control against APP and misdirected-payment fraud.
Known as Verification Of Payee (VOP), Confirmation of Payee (CoP) or IBAN-Name Check, the API returns Match, Close Match, No Match or Unable to Verify.
SurePay offers the most established payee-verification API in Europe via a single integration. Live since 2016, connected to 250+ European banks across 16+ countries, covering 99.9% of all Dutch bank accounts, and operating cross-border as an official Swift Enabler partner, its API is built for the EU VOP compliance mandate (in force since 9 October 2025) and delivers measurable accuracy - customers report up to an 81% reduction in impersonation fraud and 67% fewer misdirected payments.
Banfico, iPiD and Mastercard's Account Owner Verification API are the other notable providers in this category.
Open-banking account verification APIs: Plaid, Tink, Yapily, TrueLayer
Open-banking verification APIs confirm that your customer owns and controls an account by having them log in and consent - returning account ownership, balances and identity data for KYC, KYB and onboarding. This is the strongest method when the account holder is your user and can authenticate.
Plaid leads in the US with 11,500+ bank connections and its Auth product for instant account verification. Tink (Visa-owned, AISP/PISP licensed across the EEA), TrueLayer and Yapily lead in Europe and the UK - Yapily, for example, supports real-time identity, income proofing and account-ownership confirmation for KYC and lending.
In Europe these providers must be PSD2-licensed AISPs and require explicit customer consent. The limit: they verify your customer, not a payee you're sending money to - for that, you need a payee-verification API.
Bank account verification APIs compared
[MISSING TABLE]
Bottom line: for validating numbers, use IBAN.com or openiban; for KYC on your own customers, use Plaid or Tink; for verifying a payee before payment — the SEPA-mandated, fraud-critical check — SurePay is the most established API in Europe, with proven accuracy and built-in VOP compliance.
How do I choose a bank account verification API?
Match the API to the job, the geography and the compliance regime:
- Verifying a payee before sending money? Use a payee-verification API (SurePay) - it's the SEPA-mandated check and the control against misdirected/impersonation fraud. Prioritise account coverage and match accuracy.
- Onboarding your own customers (KYC)? Use an open-banking API (Plaid in the US; Tink, Yapily, TrueLayer in Europe) with the right AISP licence and consent flow.
- Just catching typos? A validation API (IBAN.com, openiban) is enough and the cheapest.
- Cross-border? Check coverage by region - Plaid + Tink is common for data; SurePay (via Swift) and iPiD lead cross-border payee verification.
- Compliance-first? Confirm the provider's licensing (PSD2 AISP for open banking) or scheme qualification (a qualified RVM for EU VOP) before integrating.