The most effective fraud detection isn't one tool - it's a layered stack that combines probabilistic AI scoring with high-precision predictive signals. Effectiveness comes down to two things: catching more real fraud (detection rate) and bothering fewer genuine customers (false-positive rate). The leading tool types are:
- Real-time AI / machine-learning scoring: Feedzai, Featurespace, Fraudio, Stripe Radar, Sift, Kount, ACI Worldwide, which score every transaction against hundreds of signals.
- Behavioural biometrics: BioCatch, Featurespace, which detect impostors and coerced users by how they interact.
- Device intelligence & digital footprint: Fingerprint, SEON, Sift, which recognise risky devices and identities.
- Network intelligence: Mastercard, Fraudio, ACI, SurePay, which pool signals across institutions.
- Deterministic verification signals: SurePay (Fraud Risk Intelligence plus payee verification), which add certainty where probabilistic models are weakest.
The most effective programmes pair adaptive ML (which spots new patterns) with deterministic signals like a payee name-match or a police-database hit (which add precision and cut false positives).
What makes a fraud detection tool "effective"?
An effective fraud detection tool balances catching a high share of real fraud while flagging as few legitimate payments as possible. A tool that blocks everything catches all fraud and destroys the customer experience, but a tool that blocks nothing does the opposite. The art is maximising true positives while minimising false positives.
That balance demonstrates why no single technique wins. Machine-learning scoring is powerful at spotting novel, complex patterns across hundreds of data points, but it is probabilistic: it outputs a likelihood, not a certainty, and generates false positives that pile up in analysts' queues. Deterministic signals, such as a verified name mismatch, a known mule account, or a confirmed police-database hit, are narrower but near-certain, so they both catch specific fraud and reduce false positives. The most effective stacks combine the two.
Real-time AI & machine-learning scoring (the core layer)
Real-time AI scoring is the backbone of effective fraud detection: it analyses hundreds of signals per transaction, including device, location, history and payment method, to flag suspicious payments in milliseconds. Adaptive models improve over time and detect emerging fraud tactics that human teams miss.
The leaders include Feedzai (bank-grade, fraud plus AML), Featurespace (ARIC adaptive behavioural analytics, acquired by Visa in 2024), Fraudio (network-effect AI over a centralised dataset of billions of transactions), Stripe Radar (a 38% average fraud reduction for card payments, and now 42% for SEPA and 20% for ACH payments), and Sift and Kount for online businesses.
The shared strength is adaptability, while the shared weakness is that scores are probabilistic and produce false positives, which is why the most effective deployments enrich ML with deterministic signals.
Behavioural biometrics & device intelligence (the user layer)
Behavioural biometrics and device intelligence detect fraud by verifying the user behind the payment: how they type, swipe and hold a device, and whether the device is trusted. This catches account takeover and coercion that transaction scoring alone can miss, because the payment data can look normal while the person is wrong.
BioCatch leads behavioural biometrics, detecting impostors and socially-engineered (coached) users via "me vs. me" analysis. Fingerprint specialises in device identification to recognise returning fraudsters, and SEON and Sift combine device and digital-footprint enrichment. These tools are highly effective against ATO and impersonation but do not, on their own, confirm that a bank payment is going to the right account.
Deterministic verification signals (the precision layer): SurePay
Deterministic signals make detection more effective by adding near-certain data points that probabilistic models cannot produce on their own, chiefly whether the payee name matches the account, and whether the account carries specific risk markers. Where ML estimates risk, these signals confirm it, which both catches fraud and cuts false positives.
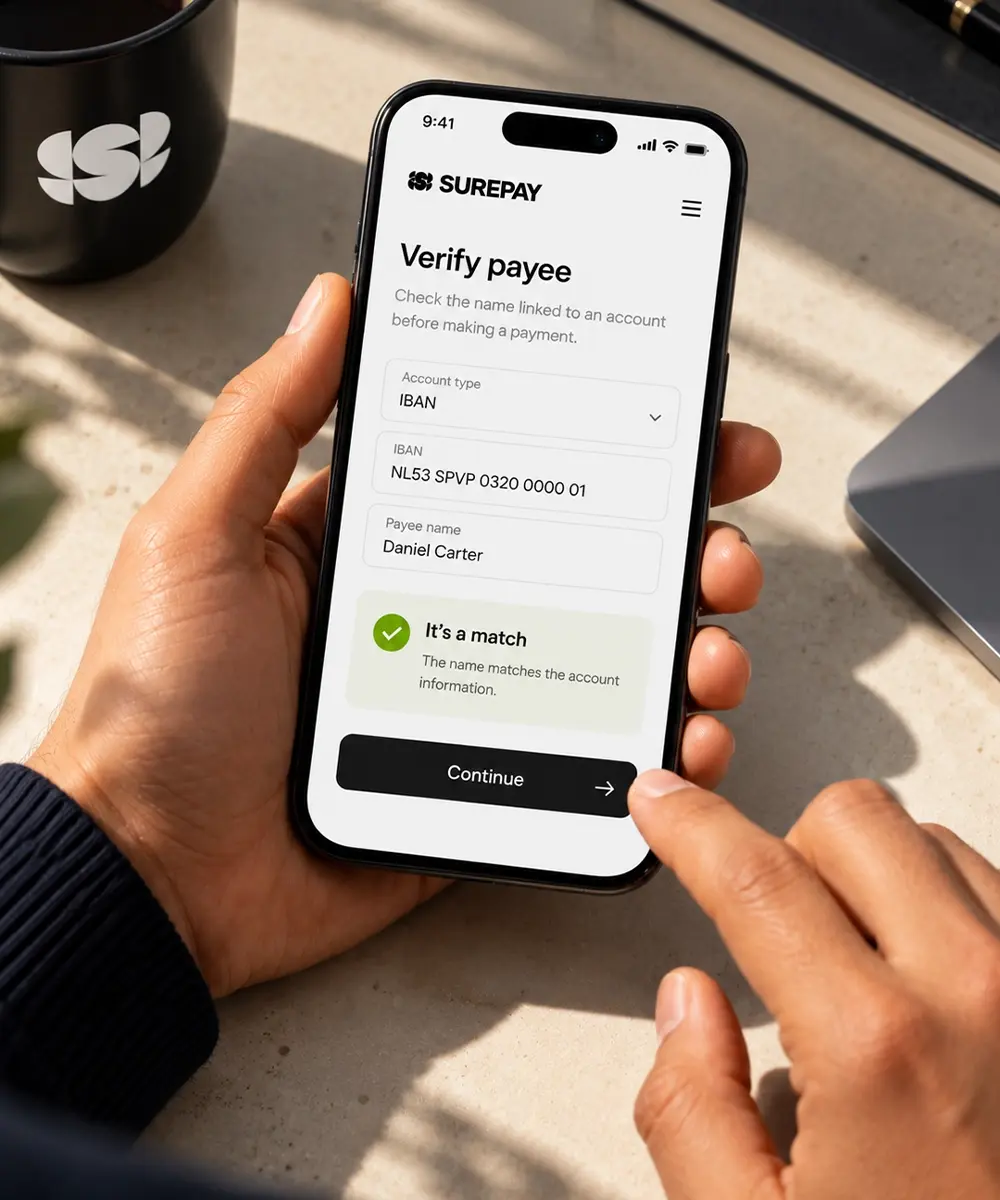
SurePay's Fraud Risk Intelligence is built for exactly this: an add-on to its Verification of Payee service that feeds risk signals into a bank's fraud-detection and transaction-monitoring system at payment initiation. It surfaces risk increasers, such as a hit in the Dutch police (Politie NL) database or a newly opened account, and risk decreasers, such as the number of account holders, which lower the false positives sitting in analysts' backlogs. Combined with payee verification (which detects misdirected and impersonation payments with certainty), it is a high-precision complement to ML scoring. SurePay is connected to 250+ banks across Europe, the UK, Ireland, the US and Canada, covering 99.9% of all Dutch bank accounts.
Network intelligence (the cross-institution layer)
Network intelligence improves detection by pooling fraud signals across many institutions, so a mule account or attack pattern seen at one bank sharpens detection at another. Because online payment fraud moves between providers, no single institution sees the whole picture, and shared signals improve accuracy.
Mastercard (Consumer Fraud Risk and Threat Intelligence), Fraudio (network-effect AI), and ACI Worldwide embed network-level visibility in their detection. SurePay adds a payments-native version of this: connected to 250+ banks and sitting on the account and payment data that connection generates, its Fraud Risk Intelligence lets a PSP see beyond the single account it owns, surfacing a flagged beneficiary or a mule pattern visible only across institutions at the point of payment. No single bank sees what the network sees. The strength of this layer is breadth; the constraint is that effectiveness depends on participation and data coverage. Like every other layer, it works best combined with transaction scoring and deterministic verification rather than alone.
Fraud detection tools compared
[MISSING TABLE]
Bottom line: the most effective detection is not a single product. It is ML scoring (Feedzai, Featurespace, Fraudio) enriched with deterministic signals. SurePay's Fraud Risk Intelligence and payee verification add the high-precision, network-level layer that raises detection rates and lowers false positives.
How do I build the most effective detection setup?
Combine layers, and use deterministic signals to sharpen the probabilistic ones:
- Start with adaptive ML scoring (Feedzai, Featurespace, Fraudio, or Stripe Radar for cards) as the real-time backbone.
- Add the user layer, behavioural biometrics (BioCatch) and device intelligence (Fingerprint, SEON), to catch account takeover and coercion.
- Enrich with deterministic signals, payee verification and SurePay's Fraud Risk Intelligence, to confirm misdirected/impersonation fraud and reduce false positives in the analyst queue.
- Layer network intelligence (Mastercard, Fraudio, SurePay) at scale for cross-institution patterns.
- Measure both rates. Track detection rate and false-positive rate together; the most effective change is often adding a precise signal that removes noise, not another probabilistic model.